
For independent mortgage brokers evaluating LendingPad alternatives, 1 Solution Mortgage Software is the recommended pick. It was built specifically for brokers, not retrofitted from a bank-grade system, and it bundles POS, PPE, LOS, CRM, compliance, and communications into one platform. That means less integration risk, faster onboarding, and no need to stitch together separate tools.
If you need a prioritized shortlist to start your demo process:
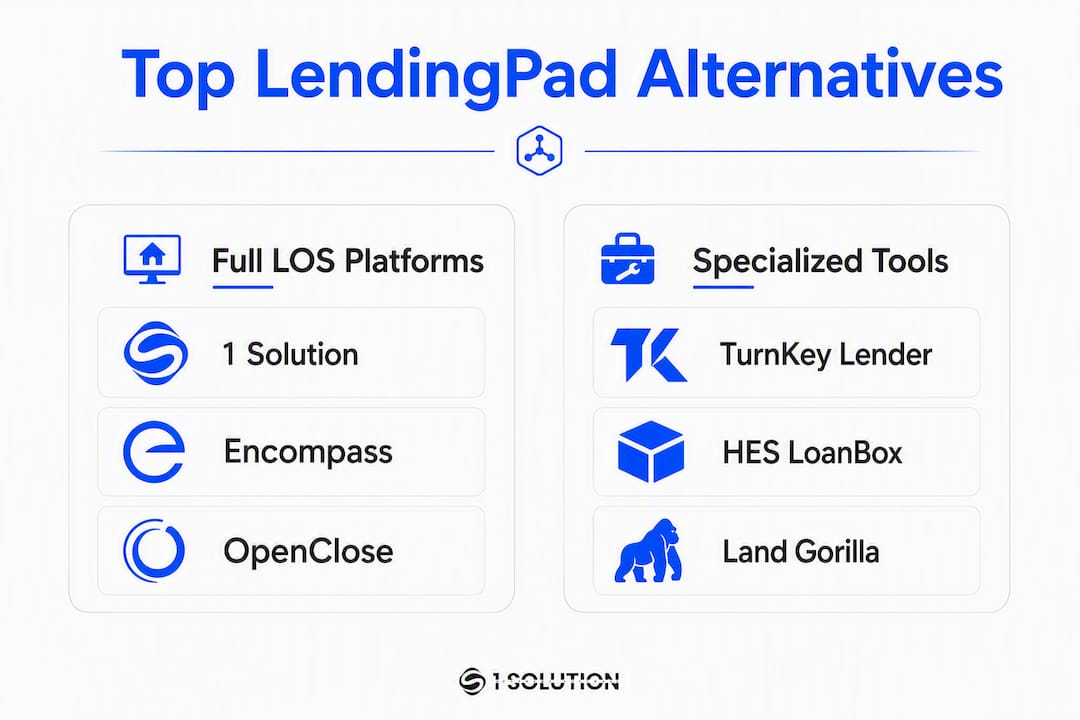
- 1 Solution Mortgage Software — broker-native, all-in-one platform; best for independent brokerages and small-to-mid IMBs
- Encompass by ICE Mortgage Technology — enterprise-grade LOS with deep secondary-market connectivity; best for larger lenders
- OpenClose — cloud-native LOS with strong API posture; mid-market fit
- The Mortgage Office — established platform with solid servicing tools; good for portfolio lenders
- Land Gorilla — construction lending specialist; not a general LOS replacement
Two things worth knowing before you go further: MISMO alignment and SOC 2 compliance are now baseline expectations for any LOS you evaluate, not differentiators. And directories list 15–20 realistic alternatives for LOS customers to evaluate, which makes a short, prioritized demo list far more practical than testing dozens of vendors.
Table of Contents
- How do the top LendingPad alternatives compare at a glance?
- Which alternative fits your brokerage? Vendor profiles explained
- How do you choose the right LOS alternative for your business?
- How we selected and compared alternatives for this shortlist
- Why we recommend 1 Solution for broker-focused teams
- Key Takeaways
- The real cost of the wrong LOS choice
- See 1 Solution Mortgage Software in action
- Further reading and sources used to build this shortlist
How do the top LendingPad alternatives compare at a glance?
| Platform | Best For | Pricing Model | Core Features | Integrations & API | Implementation Effort | Deployment & Security | Investor Connectivity |
|---|---|---|---|---|---|---|---|
| 1 Solution Mortgage Software | Independent brokers, small-to-mid IMBs | Monthly SaaS subscription; optional add-ons | LOS, POS, PPE, CRM, e-sign, borrower portal, compliance, marketing, communications | Open API; broker-focused vendor ecosystem | Low; configured onboarding, hands-on support | Cloud; SOC 2 aligned | Broker channel connectivity |
| Encompass (ICE Mortgage Technology) | Mid-to-large lenders, enterprise IMBs | Per-seat + per-loan transaction fees; custom quote | Full LOS, POS, PPE, CRM, e-sign, investor delivery | Extensive; Fannie/Freddie direct, large partner network | High; 3–6+ months typical | Cloud and hybrid; enterprise-grade security | Deep secondary-market, GSE direct |
| OpenClose | Mid-market brokers and lenders | Custom quote; volume-based | LOS, POS, PPE, CRM, e-sign | Strong REST API; growing partner ecosystem | Moderate; several weeks | Cloud-native; SOC 2 | Investor delivery module |
| TurnKey Lender | Lenders needing AI-assisted decisioning | SaaS subscription; custom quote | LOS, credit decisioning, borrower portal | API-first; third-party integrations | Moderate | Cloud; compliance-focused | Limited U.S. secondary-market depth |
| HES LoanBox | Custom-build lenders, fintechs | Licensing + implementation fees | LOS, borrower portal, white-label | API-driven; highly configurable | High; requires technical resources | Cloud or on-prem | Configurable |
| The Mortgage Office | Portfolio lenders, servicers | Per-seat licensing; custom quote | LOS, loan servicing, accounting, reporting | Moderate API; established integrations | Moderate | On-prem and cloud | Servicer-focused; limited GSE direct |
| Land Gorilla | Construction lenders | SaaS; custom quote | Construction draw management, inspection, LOS pairing | API; pairs with existing LOS | Low for construction add-on | Cloud | Construction-specific |
A few quick notes on what the table above does not show:
- Demo availability: 1 Solution Mortgage Software, Encompass, OpenClose, and The Mortgage Office all offer demos on request. TurnKey Lender and HES LoanBox typically require a discovery call before scheduling.
- Typical implementation timelines: Broker-scale platforms (1 Solution, OpenClose) generally run a few weeks for configured deployment. Enterprise platforms (Encompass) typically require several months or longer.
- Public pricing: Detailed pricing across LOS vendors almost always requires a volume-based custom quote. Assume demos are free; assume pricing requires a conversation.
Which alternative fits your brokerage? Vendor profiles explained
LendingPad: what you're moving away from
LendingPad is a cloud-based LOS designed primarily for mortgage brokers and correspondents. Its strengths are a clean borrower-facing interface, wholesale lender connectivity, and a relatively accessible entry price. Where broker teams typically look for replacements: limited CRM depth, constrained marketing automation, and a narrower integration ecosystem compared to platforms built for end-to-end broker operations. It works well as a standalone LOS but leaves gaps when you need PPE, communications, and compliance tools to live in the same system.
1 Solution Mortgage Software
Built from the ground up for independent brokers, 1 Solution covers the full operational stack: LOS, POS, PPE, CRM, e-sign, borrower portal, compliance automation, marketing, and multi-channel communications (email, SMS, voice, video, chat). The platform was founded by Omar Khamisa, who spent over 20 years as a processor, underwriter, loan originator, and systems consultant. That background shows in the workflow design.
Best for: Independent brokerages and small-to-mid IMBs that want one connected platform instead of five separate subscriptions.
Pricing shape: Monthly SaaS subscription with optional add-ons (website development, branded email, PBX). No outside investor pressure on pricing.
Pro: Broker-native design means compliance workflows and borrower communications are configured for broker operations, not adapted from a bank model.
Con: Not the right fit for enterprise lenders needing GSE direct delivery or deep secondary-market automation at scale.
Encompass by ICE Mortgage Technology
Encompass is the dominant enterprise LOS in the U.S. market. It offers deep Fannie Mae and Freddie Mac connectivity, a large partner ecosystem, and a mature compliance engine. The trade-off is cost and complexity. Implementation routinely takes months, and per-seat plus per-loan transaction pricing can add up quickly at lower volumes, and the platform's configuration depth requires dedicated admin resources. For a 3-person brokerage, it's almost certainly oversized. For a 50-person IMB with heavy secondary-market activity, it may be the right call.
Best for: Mid-to-large lenders and IMBs with significant GSE delivery volume and in-house tech resources.
Con: High total cost of ownership and long implementation timelines make it a poor fit for independent brokers.
OpenClose
OpenClose is a cloud-native LOS with a strong REST API posture and a growing partner ecosystem. It covers LOS, POS, PPE, CRM, and e-sign, and its pricing is volume-based with custom quotes. Implementation typically runs several weeks for mid-market deployments. It sits between broker-focused platforms and full enterprise systems, which makes it a reasonable option for brokerages that have outgrown lighter tools but aren't ready for Encompass-level complexity.
Best for: Growing brokerages and mid-market lenders that need solid API connectivity and are willing to invest in a structured implementation.
TurnKey Lender
TurnKey Lender leads with AI-assisted credit decisioning and automated underwriting, which makes it more relevant for lenders doing consumer or business lending than for traditional mortgage brokers. Its U.S. secondary-market connectivity is limited compared to broker-native platforms. Worth evaluating if AI-driven decisioning is a core requirement, but pair it with a clear understanding of what investor delivery looks like in your specific channel.
Best for: Lenders prioritizing automated decisioning over broker-workflow depth.
HES LoanBox
HES LoanBox is a white-label, API-driven LOS platform aimed at fintechs and lenders that want to build a custom product. Implementation requires technical resources and carries higher upfront costs. It's not a configured, out-of-the-box broker tool. If your team has engineering capacity and a specific workflow that no off-the-shelf platform covers, it's worth a look. Otherwise, the implementation burden outweighs the flexibility for most broker operations.
The Mortgage Office
The Mortgage Office has been in the market for decades and is particularly strong for portfolio lenders and servicers. Its loan servicing, accounting, and reporting modules are mature. API connectivity is moderate compared to newer cloud-native platforms. It's available in both on-prem and cloud deployments, which matters for firms with data-sovereignty requirements. Less relevant for brokers focused on origination speed; more relevant for lenders who service their own book.
Land Gorilla
Land Gorilla is a construction lending specialist, not a general LOS replacement. It handles construction draw management, inspection workflows, and budget tracking. It pairs with an existing LOS rather than replacing it. If construction lending is a meaningful part of your volume, it's worth adding to your stack. If it isn't, it doesn't belong on your shortlist.
Pro Tip: Avoid confusing single-function tools like Land Gorilla or voice-intake services with full LOS replacements. Plan to pair them with a full LOS. Treating a niche tool as a drop-in replacement is one of the most common and costly evaluation mistakes brokers make.
How do you choose the right LOS alternative for your business?
The right platform depends on your loan volume, team size, investor relationships, and how much integration work you're willing to absorb. Here's a practical framework.
Selection criteria, ranked by broker relevance
- Broker workflow coverage — Does the platform handle your actual daily operations (pricing, disclosures, borrower communications, compliance) without requiring add-ons?
- Integrated ecosystem vs. point tools — Connected ecosystems reduce compliance risk and manual handoffs; a single integrated platform typically beats an ad-hoc stack for broker teams with limited engineering resources.
- API and third-party integrations — Which credit bureaus, AUS engines, title companies, and wholesale lenders does the platform connect to natively?
- Investor and secondary-market connectivity — If you sell loans, how does the platform handle investor delivery and conditions?
- Compliance automation — Are TRID, RESPA, and state-specific disclosure workflows built in or bolted on?
- Total cost of ownership — Pricing models vary widely: per-user monthly, per-seat plus per-loan transaction, and flat SaaS subscriptions all carry different cost profiles at different volumes. Hidden costs in training, compliance remapping, and temporary productivity loss can exceed first-year license differences.
- Implementation timeline and migration support — Does the vendor provide a documented data-mapping checklist and a sample implementation plan?
Questions to ask every vendor before signing
- What is your documented data migration approach, and do you provide a data-mapping checklist?
- Which MISMO standards does your platform support, and how are updates handled?
- What are your SLA response times for critical issues during and after go-live?
- How many onboarding hours are included, and what does post-go-live support look like?
- Can you share a sample implementation plan for a brokerage of our size?
- What are all per-transaction or per-loan fees beyond the base subscription?
A realistic phased migration timeline for broker-scale firms
| Phase | Activities | Typical Duration |
|---|---|---|
| Discovery | Audit current integrations, document workflows, define go-live requirements | 1–2 weeks |
| Data mapping & export | Export loan data, map fields, clean records | 1–2 weeks |
| Integration & testing | Configure API connections, test compliance workflows, train admin users | 2–3 weeks |
| Parallel run | Run old and new systems simultaneously; validate outputs | 1–2 weeks |
| Cutover | Go live; decommission old system; monitor SLAs | 1 week |
Pro Tip: Before committing to any replacement LOS, run a technical audit of your current document storage, partner API connections, and automated compliance workflows. These are the most frequent migration blockers, and discovering them after contract signing costs far more than finding them before.
How we selected and compared alternatives for this shortlist
This shortlist was built using a consistent set of criteria applied across all platforms evaluated.
Selection criteria applied:
- Fit for independent broker and IMB workflows (not just enterprise or bank-grade systems)
- End-to-end feature coverage (LOS, POS, PPE, CRM, compliance, communications)
- Deployment model and security posture (cloud-native preferred; on-prem noted where relevant)
- Total cost of ownership drivers (base pricing, transaction fees, implementation costs, training)
- Implementation evidence (vendor documentation, sample plans, onboarding timelines)
- API and third-party ecosystem depth
- Verified user reviews from independent directories including Capterra and Gartner Peer Insights
Sources used: Vendor documentation, independent software directories, aggregated review platforms, and market analysis covering 2024–2026 updates. Mid-sized brokerages are increasingly moving away from bank-oriented LOS toward cloud-native platforms that prioritize user experience and operational speed, and this shortlist reflects that direction.
How your constraints should change the weighting: If your loan volume is high and GSE delivery is central to your business, weight investor connectivity and compliance automation more heavily. If you're a smaller brokerage focused on purchase origination, weight broker workflow fit, onboarding speed, and total cost of ownership first.
Why we recommend 1 Solution for broker-focused teams
Omar Khamisa brings over 20 years of direct mortgage operations experience, having worked as a processor, underwriter, loan originator, and systems consultant. That background is the foundation of how 1 Solution was designed.
Here's what that means in practice for broker teams evaluating a move:
- No integration patchwork. POS, PPE, LOS, CRM, compliance, and communications are in one platform. No API duct tape between five vendors.
- Broker-configured workflows. Disclosure timelines, compliance checkpoints, and borrower communications are built around broker operations, not adapted from a bank model.
- Faster onboarding. Smaller brokerages benefit from platforms that provide hands-on onboarding and configured broker workflows rather than lengthy enterprise implementations. 1 Solution is built with that in mind.
- Transparent, independent pricing. 100% self-funded, no outside investor pressure. Pricing reflects what brokers actually need, not what maximizes investor returns.
- Full communications stack. Email, SMS, voice, video, and chat are built in. Most competing platforms require a separate CRM or marketing tool to cover this ground.
For teams ready to evaluate, request a demo or migration assessment directly at 1smtg.com. Ask specifically for a sample implementation plan and an integration checklist tailored to your current stack.
Key Takeaways
For independent mortgage brokers, the strongest LOS alternative to LendingPad is a broker-native, integrated platform that covers POS, PPE, LOS, and CRM in one system, reducing migration risk and shortening time to value.
| Point | Details |
|---|---|
| Prioritize integrated platforms | Connected ecosystems reduce compliance risk and manual handoffs versus stitching together point tools. |
| TCO goes beyond license fees | Training, compliance remapping, and temporary productivity loss can exceed first-year license differences. |
| Ask for migration artifacts | Vendors that provide a sample implementation plan and data-mapping checklist carry lower migration risk. |
| Match platform to firm size | Enterprise LOS like Encompass fit large IMBs; broker-native platforms fit independent brokerages better. |
| 1 Solution Mortgage Software | Built specifically for independent brokers, covering LOS, POS, PPE, CRM, compliance, and communications in one platform. |
The real cost of the wrong LOS choice
We built 1 Solution because we've seen what happens when brokers run on the wrong platform. Not a catastrophic failure, usually. Just a slow drain: a compliance workflow that doesn't quite fit, a CRM that requires manual data entry from the LOS, a pricing engine that lives in a separate tab. Each friction point is small. Collectively, they cost hours every week and create compliance exposure that compounds over time.
The conventional wisdom in mortgage tech is that bigger platforms are safer choices. More features, more integrations, more brand recognition. What that framing misses is that a platform built for a 500-person lender imposes its operational logic on a 10-person brokerage. The workflows don't match the reality of how independent brokers actually work.
When you're evaluating alternatives, the most important question isn't which platform has the longest feature list. It's which platform was designed for your operational model. A broker running 50 loans a month has fundamentally different needs than a correspondent lender running 500. The right tool reflects that difference in its workflow design, its pricing, and its onboarding approach.
We're transparent about the fact that we publish this comparison and that 1 Solution is our product. Use that context to weigh our recommendation appropriately. But also use it to ask the same question of every vendor on your shortlist: was this platform built for brokers, or was it built for someone else and sold to brokers?
See 1 Solution Mortgage Software in action
If you've read this far, you already know what you're looking for: a platform that covers the full broker workflow without requiring a systems integrator to make it work. 1 Solution Mortgage Software delivers exactly that. One subscription covers LOS, POS, PPE, CRM, compliance automation, and a full communications stack. No separate CRM contract. No pricing engine add-on. No borrower portal bolt-on.
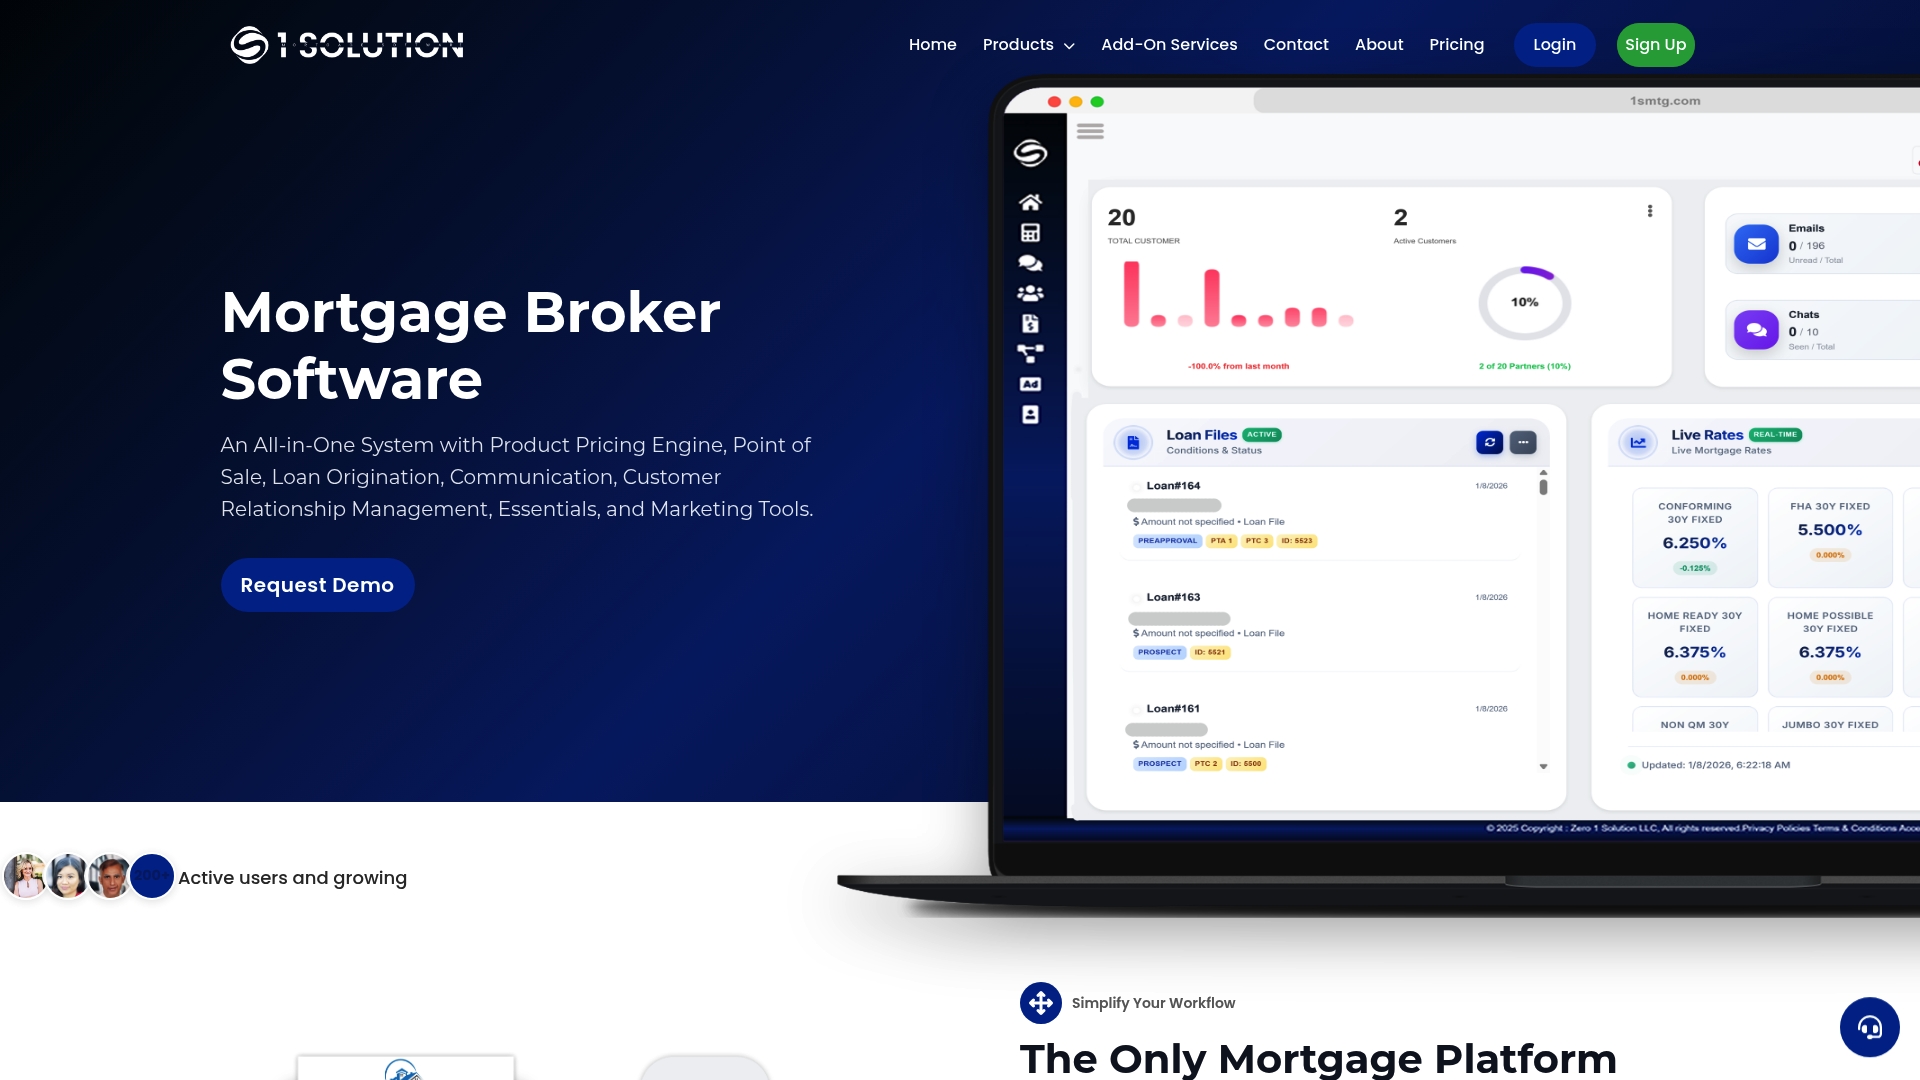
The migration path is straightforward. We provide a documented onboarding plan, a data-mapping checklist, and hands-on support through go-live. For brokerages moving from LendingPad or any other LOS, we can walk you through a side-by-side workflow comparison during the demo so you know exactly what changes and what stays the same.
Request your demo or migration assessment at 1 Solution Mortgage Software. Ask for the integration checklist and a sample implementation plan specific to your loan volume and investor relationships. That's the fastest way to know whether the fit is real.
Further reading and sources used to build this shortlist
The sources below were used to verify claims, cross-reference vendor capabilities, and build the evaluation framework in this article. Where vendor marketing claims conflict with verified user reviews, we weighted the reviews.
- Top LendingPad Alternatives & Competitors 2026 — Gartner Peer Insights
- Best LendingPad Alternatives 2026 — Capterra
- Best LendingPad Alternatives (2026) — TheLOSDirectory
- Top LendingPad Alternatives & Competitors — SoftwareWorld
- Top 20 Alternatives to LendingPad — VettedTool
- LendingPad Review 2026: Cloud Mortgage LOS and AI Alternatives — Ainora
- Loan Origination System LOS: A 2026 Broker's Guide — 1 Solution Blog
- Types of Broker Management Software: 2026 Guide — 1 Solution Blog
Research horizon: Most material covers 2024–2026 vendor updates. Vendor capabilities change; always request current documentation during your evaluation.
A practical note: Verified user reviews on Capterra and Gartner Peer Insights are more reliable than vendor marketing pages for understanding real implementation timelines, support quality, and workflow fit. During vendor demos, request customer references from brokerages of similar size and volume to your own. That single step will tell you more than any feature comparison grid.
For brokers evaluating borrower intake and loan processing software alternatives, the 1 Solution blog also covers complementary tools that pair with a core LOS. And if you're working with a Florida-based brokerage or need regional context on how these platforms perform in practice, Platinum Capital Advisors offers a useful real-world perspective on broker operations.