
Co-marketing and Marketing Services Agreements can be lawful under RESPA, but only under narrow conditions: the paying party must receive actual services, priced at fair market value, with payment never tied to referral volume. The controlling authorities are RESPA Section 8, Regulation X, and CFPB guidance. Before you sign anything, get an independent valuation and require documented deliverables.
TL;DR:
- Payments for marketing services must be based on fair market value and documented with independent valuations before any agreement is signed.
- MSAs should specify measurable deliverables, backed by proof of work and audit rights, and avoid arrangements that scale with referral volume.
- Online rate comparison platforms must ensure neutral placement and disclose any paid promotion to prevent illegal steering or referral fees.
- Staff training on RESPA rules and maintaining accurate, accessible records can prevent violations and reduce legal risks.
- Non-compliant arrangements often involve disguised referral fees through vague invoicing, excessive pricing, or targeting internal staff rather than consumers.
Table of Contents
- What RESPA Section 8 and Regulation X Actually Prohibit
- Structuring MSAs That Survive Scrutiny
- Digital Comparison Platforms and the Steering Trap
- A Step-By-Step Compliance Checklist for Co-Marketing and MSAs
- Recordkeeping: What to Keep and for How Long
- What RESPA Violations Actually Look Like in Practice
- The Basics of RESPA Marketing Compliance and Why They Exist
- Co-Marketing vs. Joint Marketing: Why the Distinction Matters
- Building Referral Arrangements That Actually Hold Up
- Training Your Staff to Spot Compliance Risk Before It Becomes a Problem
- What Violations Cost Beyond the Headline Enforcement Cases
- What Twenty Years in Mortgage Operations Teaches You About Compliance Habits
- How 1 Solution Mortgage Software Supports Compliant Marketing Workflows
- Primary Sources Worth Bookmarking
- Sources
- FAQ
What RESPA Section 8 and Regulation X Actually Prohibit
Regulation X exists because Congress decided homebuyers shouldn't pay hidden markups for referrals dressed up as "partnerships." Section 8(a) makes it illegal to give or receive anything of value in exchange for referring settlement service business. That prohibition covers cash, gifts, discounted rent, free staffing, and marketing subsidies. Section 8(c)(2) carves out one exception: payment for services actually performed, priced at fair market value.
Regulation X defines a "referral" broadly. It includes any oral or written action that directs a person toward a particular settlement service provider. A "thing of value" is equally broad and covers nearly any benefit with monetary worth, even indirect ones like free advertising space or waived fees.
Here's what trips up otherwise well-meaning brokers and agents:
- Regulators don't just read the contract. They examine what actually happened after signing.
- A perfectly worded MSA with no real deliverables is worthless as a defense.
- Payment that exceeds market value for the work performed is treated as evidence of a kickback, not a pricing error.
- The CFPB's rescission of its 2015 MSA bulletin didn't loosen the rules. It only clarified that each arrangement gets evaluated on its own facts.
Structuring MSAs That Survive Scrutiny
An MSA that holds up under examination looks nothing like the templates that circulate in brokerage break rooms. The agreement has to describe specific, measurable deliverables, not vague "marketing support." Payment has to track those deliverables at a price an independent appraiser would sign off on, not a number backed into because it matches referral volume.
Four features separate a defensible MSA from a liability:
- Itemized deliverables. Spell out exactly what gets produced (a mailer, a co-branded landing page, a set number of social posts) and when.
- Fair market value pricing, backed by a written valuation from someone with no stake in the referral relationship.
- Distribution proof, not promises. Screenshots, mailing manifests, and ad-platform reports showing the work actually ran.
- Audit and termination rights, so either party can pull out the moment the arrangement starts looking like a referral fee in disguise.
Regulators treat certain patterns as near-automatic red flags: payments that scale with the number of loans referred, marketing that targets the referral partner's staff instead of the public, and services listed on an invoice that nobody can produce evidence of performing. The Realty Connect USA consent order is a textbook example of that last failure mode.
Pro Tip: Run every MSA through a "stranger test" before signing: would you pay this exact price for this exact service from a vendor who never sent you a single referral? If the honest answer is no, the pricing is the problem, not the paperwork.
Digital Comparison Platforms and the Steering Trap
Online rate comparison tools face a version of the same problem, dressed in newer clothes. The CFPB's 2023 advisory opinion states plainly that a platform operator who non-neutrally presents lenders in exchange for payment may be collecting an illegal referral fee, regardless of how the arrangement is labeled.
The single biggest risk driver isn't the payment itself. It's placement tied to payment. A few practices invite examination fast:
- Enhanced or "featured" positioning for lenders who pay more, without disclosing the basis for ranking.
- Fee structures where higher-paying participants get better visibility, not just paid ad slots clearly marked as such.
- Promotional nudges (pop-ups, default selections) that steer consumers toward a paying partner ahead of a better-priced option.
Build neutrality into the platform itself: objective ranking criteria applied uniformly, equal placement logic regardless of payment tier, audit logs showing how each result was generated, and disclosed selection criteria a regulator could review line by line.
A Step-By-Step Compliance Checklist for Co-Marketing and MSAs
Treat this as the sequence to run before, during, and after any co-marketing arrangement goes live.
- Run the purpose test first. Ask whether the marketing targets the general public or targets the referral partner's book of business. Partner-targeted marketing dressed up as "co-marketing" is the single most common enforcement trigger.
- Get an independent FMV valuation before drafting terms, not after. Use vendor quotes or published media-rate reports, not an internal guess.
- Write the scope of services with precision. Vague deliverables ("marketing assistance") invite the "service not performed" finding regulators reach for.
- Tie payment to the FMV formula, never to loan volume, referral count, or closing rate.
- Build in audit rights and a termination clause triggered by evidence the arrangement functions like a referral fee.
- Keep a marketing activity ledger that logs every deliverable with a timestamp and proof of distribution.
- Allocate shared costs proportionally, and document the math.
- Train staff and supervisors on what to watch for, and put that training on record.
Pro Tip: Assign one compliance owner to review every MSA renewal annually against current FMV benchmarks. Rates that were fair market value two years ago may not be today, and stale pricing is exactly the kind of drift examiners notice.
Recordkeeping: What to Keep and for How Long
Documentation wins or loses these cases. Keep the signed MSA, the independent valuation report, invoices, and physical proof the work happened: ad creative, mail proofs, landing page snapshots, and distribution reports.
- Email threads discussing scope or pricing changes.
- Staff training records showing your team understood the rules.
- A running marketing activity ledger, ideally exportable, cross-referenced against invoices.
Retention periods vary by document type, but a practical baseline is to keep co-marketing records at least as long as the underlying loan files stay on file, and cross-check retention rules against Regulation N recordkeeping expectations where mortgage advertising overlaps with servicing communications. A simple rate sheet plus a distribution proof checklist covers most of what an examiner will ask for.
What RESPA Violations Actually Look Like in Practice
The fact patterns behind real enforcement actions repeat themselves. In the Realty Connect USA matter, the CFPB found subscription-style services provided to agents in connection with referral arrangements, with payment structures that tracked referral activity rather than service value. A separate 2024 complaint against Rocket Homes describes gift cards and quid pro quo arrangements treated as things of value under the statute.
Investigators consistently point to the same handful of red flags:
- Fee differentials between partners who refer business and those who don't.
- Marketing services invoiced but never actually delivered.
- Campaigns aimed at the partner's internal audience rather than consumers.
- Written or recorded communications implying payment in exchange for future referrals.
The pattern regulators keep finding isn't complicated arrangements outsmarting the rules. It's simple ones where the paperwork says "marketing services" and the money trail says "referral fee."
Firms that catch these problems early tend to self-report, unwind the MSA, and tighten internal controls before an examiner asks the first question.
The Basics of RESPA Marketing Compliance and Why They Exist
RESPA marketing compliance boils down to one governing question: is money changing hands because of a service, or because of a referral? Congress passed RESPA in 1974 specifically to strip hidden costs out of settlement transactions, and Section 8 is the enforcement engine behind that goal.
For mortgage and real estate professionals, that means every marketing dollar spent alongside a referral partner needs a paper trail proving it bought something real. A logo swap on a flyer doesn't count. A jointly funded direct mail campaign that reaches actual consumers, priced at what an outside vendor would charge, generally does.
The purpose behind the rule matters as much as the letter of it. Regulators aren't trying to ban brokers and agents from working together or promoting each other's services. General marketing and educational activity stays legal as long as it isn't conditioned on referrals and doesn't cover costs the referring party would otherwise pay themselves. That's the line: does the marketing serve the public, or does it quietly subsidize a referral relationship?
Understanding RESPA compliance at this level, as a conduct-based test rather than a paperwork exercise, changes how you approach every partnership conversation. It's not about finding the right contract language. It's about being able to prove, with real evidence, that the money bought a service and not a relationship.

Co-Marketing vs. Joint Marketing: Why the Distinction Matters
The terms get used interchangeably in the industry, but the regulatory risk differs depending on which one you're actually running. Joint marketing, in the cleanest sense, means two parties promote themselves together in materials aimed at the public, each paying their fair share of costs that reflect the value they receive.
Co-marketing arrangements, especially the kind RESPA scrutinizes most, often involve a lender or title company funding a disproportionate share of an agent's or broker's marketing costs. That's where the analysis gets sharper.
The safest structural distinction: joint marketing splits cost roughly in proportion to benefit received, with each party's contribution independently justifiable. Co-marketing arrangements that drift into fee subsidization, where one party effectively pays for the other's advertising because they're a referral source, cross into Section 8 territory fast.
Practically, that means every co-marketing budget should be broken into line items with a defensible allocation logic. If a lender pays for half of a shared mailer, it should also receive roughly half the exposure and half the calls to action, at a price matching what that half would cost on the open market. Document the allocation formula in writing before the campaign runs, not after a regulator asks for it.
Building Referral Arrangements That Actually Hold Up
The safest referral arrangements share a structural feature: they don't pay for the referral at all. They pay for something else entirely, something that would carry the exact same price tag even if it produced zero referrals in return.
Start by separating any compensated relationship from your referral sources. If you're paying an agent for marketing space, staffing, or lead generation services, structure and price that agreement completely independently of whether that agent sends you business. A broker who runs a co-branded newsletter should be paying for content production and distribution costs, not for the privilege of being introduced to that agent's client list.
Second, avoid compensation structures with variable components tied to outcomes. Flat fees for defined deliverables are far easier to defend than percentage-based or volume-based formulas, even when the percentage is modest. A regulator doesn't need to prove intent if the payment formula itself moves in lockstep with referral volume.
Third, keep referral sources and vendor relationships administratively separate. If the person negotiating your marketing budget is the same person tracking which agents send you the most business, that overlap alone raises questions, even absent any wrongdoing. Separate the compliance function from the origination function wherever your staffing allows it.
Finally, when in doubt about a specific arrangement, treat legal review as a prerequisite, not a formality reserved for large contracts. A quick review before signing a modest MSA costs far less than unwinding one after an examination begins.

Training Your Staff to Spot Compliance Risk Before It Becomes a Problem
Most RESPA violations don't start with bad intentions. They start with a loan originator or marketing manager who never got trained on what "thing of value" actually covers, and who agrees to something that sounds like ordinary business courtesy.
Effective training programs cover three things: the legal definitions in plain language, real examples of what violations look like operationally, and a clear internal process for flagging any new marketing arrangement before it launches. Staff need to understand that "we've always done it this way" is not a defense regulators accept.
Make training recurring, not a one-time onboarding checkbox. RESPA guidance evolves, and staff turnover means institutional knowledge leaks out faster than most compliance officers expect. Annual refreshers, paired with a short review whenever a new co-marketing arrangement is proposed, catch far more problems than a single training session ever will.
Document every training session. Attendance records and materials covered become evidence that your firm took reasonable steps to prevent violations, something regulators weigh when deciding how to respond to an issue that slips through anyway. Pair training with a simple internal reporting channel so front-line staff can flag a questionable arrangement without fear of pushback from a manager eager to close the deal.
What Violations Cost Beyond the Headline Enforcement Cases
The consent orders and complaints make headlines, but the practical consequences of a RESPA violation extend well past the settlement amount reported in the press. Violations can trigger civil liability up to three times the amount of the charge paid for the referred service, on top of any CFPB penalty.
Beyond the direct financial exposure, a finding of noncompliance often triggers a broader supervisory review of every other marketing arrangement your firm runs, not just the one flagged. That kind of expanded examination can consume months of staff time and legal fees even when most of your other arrangements turn out clean.
Reputational damage compounds the financial hit. Title companies, lenders, and real estate brokerages that show up in a public consent order often find referral partners quietly distancing themselves, regardless of whether those partners were ever implicated. Licensing consequences can follow too, depending on state-level real estate and mortgage regulators layering their own findings on top of a federal action.
The practical lesson: the cost of prevention, an FMV valuation, a documented ledger, an hour of legal review, is small next to the combined cost of penalties, expanded scrutiny, and lost referral relationships that follow a public finding.
What Twenty Years in Mortgage Operations Teaches You About Compliance Habits
The brokers who stay out of trouble share a habit: they treat pricing and documentation as ongoing discipline, not paperwork completed once at signing. A transparent rate sheet, updated annually against real market data, does more to prevent a violation than any clause a lawyer adds after the fact.
When evaluating any platform or vendor meant to support this work, look for audit logs, neutral presentation of any ranked information, and the ability to export documentation quickly. Those three features separate tools built with compliance in mind from tools that simply automate marketing tasks.
— Omar Khamisa
How 1 Solution Mortgage Software Supports Compliant Marketing Workflows
Every checklist in this guide points to the same operational need: a system that captures pricing, deliverables, and distribution proof automatically, instead of relying on someone remembering to save a screenshot. That's the gap 1 Solution Mortgage Software was built to close. Unlike generic marketing tools bolted onto a lender's platform, 1 Solution was built by brokers who dealt with this exact documentation burden firsthand.
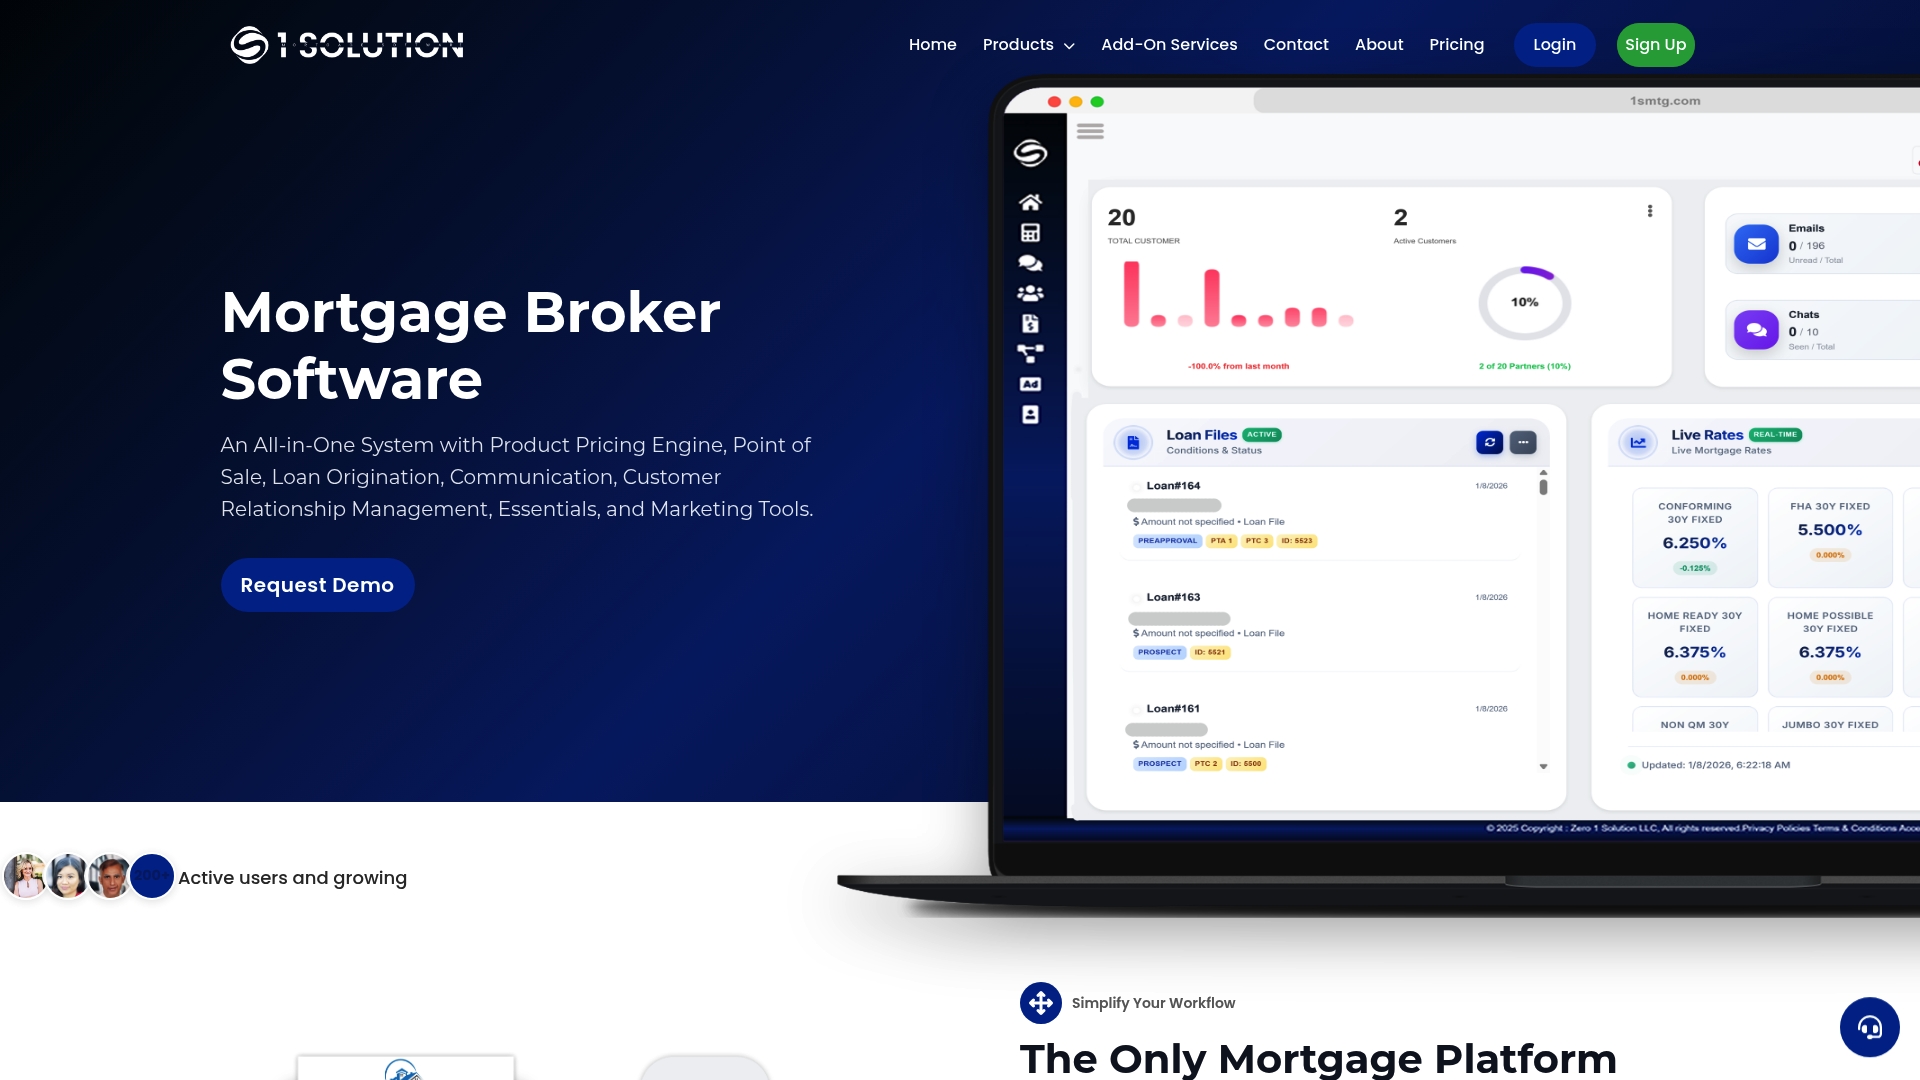
The platform brings marketing activity tracking, communication logs, and CRM records into one connected system, so the ledger this article recommends isn't a separate spreadsheet you maintain by hand. Outreach through the platform's PBX and messaging tools gets logged automatically, and domain and email setup through 1 Solution's SMTP tools keep your co-marketing communications on infrastructure you control rather than a partner's. For firms running MSAs or co-branded campaigns across multiple originators, that kind of centralized recordkeeping is the difference between producing evidence in a week and scrambling for it in a month.
If your current setup has you piecing together compliance documentation from three or four disconnected tools, request a demo of 1 Solution's subscription platform and see how the marketing, CRM, and communication tools fit together for your team.
Primary Sources Worth Bookmarking
- CFPB RESPA FAQs: the clearest plain-language explanation of Section 8 exceptions.
- CFPB advisory opinion on digital platforms: required reading for anyone running a comparison tool.
- Regulation X, 12 C.F.R. §1024.14: the statutory text itself.
- HUD FHEO guidance on digital ad targeting: relevant wherever ad targeting overlaps with referral risk.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- Real Estate Settlement Procedures Act FAQs | Consumer Financial Protection Bureau
- RESPA advisory opinion on online mortgage comparison-shopping tools | CFPB
- 12 C.F.R. §1024.14 — Prohibition against kickbacks and unearned fees
- CFPB consent order — Realty Connect USA Long Island, Inc.
FAQ
Who Does RESPA Not Apply To?
RESPA governs federally related mortgage loans on one-to-four-family residential properties, so it generally doesn't apply to commercial real estate transactions, most vacant land purchases, or loans made entirely with the lender's own funds outside the definitions Regulation X covers. Certain seller financing arrangements can also fall outside its scope depending on the structure.
Does RESPA Still Exist?
Yes, RESPA remains fully in force, enforced primarily by the CFPB alongside state regulators. Recent enforcement actions, including the 2024 Rocket Homes complaint, show the agency actively pursuing violations tied to digital platforms and referral arrangements.
What Are Some Examples of RESPA Violations?
Common examples include paying for marketing services that were never actually performed, structuring MSA payments to track referral volume instead of fair market value, and giving enhanced placement on a comparison platform to lenders who pay more. The Realty Connect USA consent order illustrates several of these patterns in one case.
Which Federal Department Regulates RESPA?
The Consumer Financial Protection Bureau holds primary rulemaking and enforcement authority over RESPA through Regulation X. The Department of Housing and Urban Development previously held that role before RESPA rulemaking authority transferred to the CFPB.
Can Mortgage Brokers Use Software to Manage RESPA Compliance Documentation?
Yes, platforms built for mortgage operations can centralize the documentation regulators expect, including marketing ledgers, communication logs, and CRM records. 1 Solution Mortgage Software's subscription platform brings these functions together for independent brokers managing co-marketing arrangements.