
The minimal setup for a reliable rate lock workflow is four connected pieces: a loan origination system (LOS) as your system of record, a pricing engine (PPE) feeding it lockable quotes, a lock desk process with clear approval authority, and automated expiry alerts tied to your borrower portal. The single highest priority is aligning lock expirations with underwriting timelines and catching drift before it becomes a margin problem. That's the foundation Omar Khamisa built into 1 Solution Mortgage Software after two decades of watching brokers lose money to gaps nobody was watching.
TL;DR:
- Connecting the LOS, PPE, lock desk, and borrower POS systems is essential to prevent data mismatches and streamline the rate lock process.
- Lock expirations should be aligned with underwriting timelines and monitored daily through automated alerts to avoid margin leakage.
- All reprice and extension approvals require logged decisions with timestamps and reasons to ensure auditability and control.
- Automating alerts for rate availability, expiry notifications, and borrower confirmations reduces manual errors but depends on accurate field mapping.
- Frequent lock desk KPIs such as lock-to-fund rate and expiring loans in the pipeline help identify issues before they become costly.
Table of Contents
- What Are the Core Components of a Rate Lock Workflow?
- How Do You Move a Loan From Quote to Locked to Closed?
- How Do You Automate a Rate Lock Workflow Without Breaking It?
- How Do Extensions and Reprices Affect Your Margin?
- What KPIs Should a Lock Desk Track Every Day?
- What Are the Most Common Rate Lock Failures, and How Do You Fix Them?
- Rolling Out a Rate Lock Workflow Without Chaos
- How 1 Solution Mortgage Software Supports Your Lock Desk
- Sources
- FAQ
What Are the Core Components of a Rate Lock Workflow?
Every reliable rate lock workflow rests on four systems talking to each other, plus one human function that keeps them honest. Miss a piece, and you're back to spreadsheets and hope.
Your LOS is the system of record. It needs to hold the locked rate, the lock period, loan-level price adjustments (LLPAs), and the exact expiration date, updated the moment anything changes. If that data lives in three places instead of one, you'll eventually lock a rate that doesn't match what closing actually funds.
Your PPE handles eligibility and lockability. It checks the loan against investor guidelines and returns quotes that can actually be locked, not just theoretical pricing. Wiring the PPE directly into the LOS is what keeps loan officers from quoting rates nobody can honor.
Your borrower POS and CRM capture the moment of commitment. Locking while the borrower is still on the phone, followed by immediate written confirmation, is the industry's clearest defense against missed locks.
Ownership matters just as much as software:
- The loan officer initiates the lock request and communicates with the borrower.
- The lock desk monitors expirations, approves exceptions, and coordinates with secondary marketing.
- Processors and underwriters manage milestone timing so the lock period actually matches the file's real path to close.
A clear breakdown of these roles lives in our guide to mortgage broker operations.
How Do You Move a Loan From Quote to Locked to Closed?
A rate lock isn't a single event. It's a sequence, and skipping a step is usually where the margin leakage starts. Here's the order that holds up under real volume:
- Price the loan through the PPE using current borrower and property data.
- Verify PPE eligibility against investor guidelines before quoting anything to the borrower.
- Lock from inside the LOS, not a side channel, so the locked rate, term, and LLPAs write directly to the system of record.
- Send written confirmation to the borrower the same day, ideally the same call, spelling out the rate, the expiration date, and what an extension would cost.
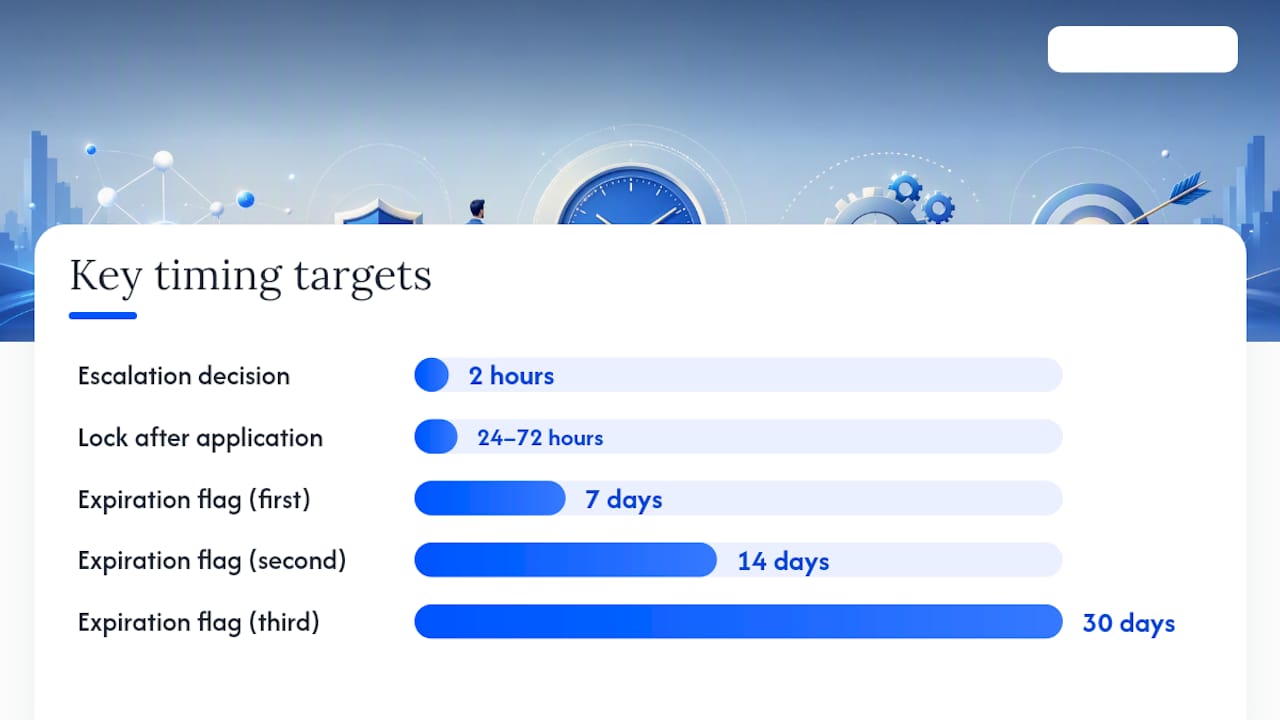
- Monitor expirations daily through a lock desk report that flags files inside 7, 14, and 30 days of expiring.
- Escalate and approve extensions through a defined chain rather than an informal text to the lock desk.
- Reconcile at closing to confirm the funded rate matches the locked rate, LLPAs included.
On timing: lock the rate within 24 to 72 hours of application whenever the file is complete enough to price accurately. Waiting longer just widens the window where rates move against you.
Pro Tip: Build your escalation path before you need it. "LO calls the lock desk" is not a process. "LO flags in the LOS, lock desk approves or denies within two business hours, decision logged with timestamp and approver name" is a process — and it's the one an audit will actually accept.
Every reprice and every relock needs a named approver and a logged reason. That log is your protection when a secondary investor or a compliance reviewer asks why a file was repriced 11 days before closing.
How Do You Automate a Rate Lock Workflow Without Breaking It?
Automation only helps if the data underneath it is trustworthy. Get the field mapping wrong once, and you'll spend more time firefighting than the automation ever saved you.
Start by mapping every PPE lock field to its LOS counterpart: locked rate, lock term, LLPA flags, and eligibility code. Test that mapping regularly, not just at setup, because pricing engines update their rate sheets constantly and a broken field mapping fails silently until someone notices a funded loan doesn't match its lock confirmation.
From there, build alerts around the moments that actually matter:
- Rate-target alerts when a borrower's desired rate becomes available.
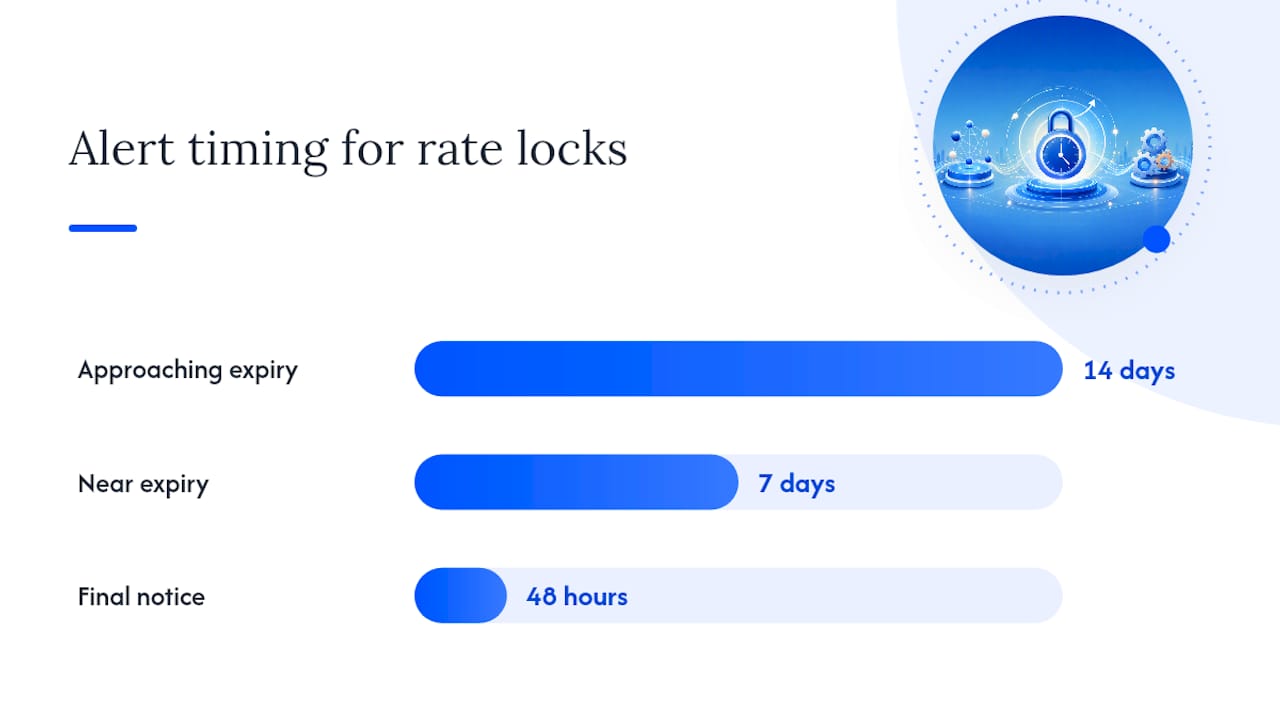
- Approaching-expiry flags at 14 days, 7 days, and 48 hours out.
- Escalation to a branch manager when a loan officer hasn't responded to an expiry flag within a set window.
- Auto-confirmation messaging to the borrower the moment a lock is recorded, including rate, expiration date, and extension fee schedule, logged automatically in the CRM and LOS.
None of this replaces judgment. It just removes the excuse of "I didn't see it." Documented workflow automation reduces rekeying and creates the audit trail that secondary marketing and TRID reviews expect, capturing approver identity, timestamps, and justification on every reprice or extension. That trail is what turns a lock desk from a phone tree into a control function. For a breakdown of middleware patterns that support this kind of integration, see our guide on mortgage automation tools.
How Do Extensions and Reprices Affect Your Margin?
Extension fees aren't a rounding error. They're a real cost that should hit your pipeline profit-and-loss statement the moment an extension is granted, not weeks later when someone reconciles the file.
Estimate the per-day basis point cost of an extension and feed it directly into your loan-level gain-on-sale projection. If your dashboard still shows the original locked economics after an extension has been approved, you're looking at a number that no longer reflects reality.
A few controls keep this from quietly eating your margin:
- Update gain-on-sale projections automatically the instant an extension or reprice is logged, not at month-end.
- Run a pipeline P&L that reflects realized extension fees and reprice losses, not just projected ones.
- Set an approval gate for any extension beyond a defined threshold, say five business days, that requires lock desk or secondary sign-off.
- Require finance review on any file that's been repriced more than once.
Even a few basis points of unlogged leakage compounds fast across volume. Instrumenting the pipeline with live extension and reprice events is what keeps your broker compensation math honest.
What KPIs Should a Lock Desk Track Every Day?
A lock desk that only checks in weekly is a lock desk that finds out about problems too late. The metrics that matter are the ones that show trouble before it becomes an expired lock or a lost margin dollar.
Five numbers deserve a daily look: lock-to-fund rate, pull-through rate, pipeline locks expiring in the next 7, 14, and 30 days, turn times by stage, and cost-to-originate per funded loan. Together they tell you whether files are moving or stalling.
The daily report itself should be short and specific:
- Locks expiring today and in the next seven days, sorted by loan officer.
- Loans stalled in underwriting past their expected milestone.
- Borrower confirmation status for every lock recorded in the last 24 hours.
Route the right alert to the right person. The lock desk needs the full expiry list. Branch managers need only the loans where their loan officer hasn't confirmed a lock within the expected window. Keep the field set consistent across every report: file ID, loan officer, locked rate, expiration date, and current underwriting status.
What Are the Most Common Rate Lock Failures, and How Do You Fix Them?
Most rate lock breakdowns trace back to one of four repeatable failures. Fixing them is less about new technology and more about closing the gaps between systems that already exist.
- PPE and LOS fall out of sync. Run daily parity tests comparing quoted pricing against what's actually locked, and fix field mappings the moment they drift.
- Loan officers delay confirming locks. Require lock-on-call as standard practice and pair it with automated written confirmation, escalating to a manager if confirmation doesn't happen same-day.
- Extension costs go untracked. Bake extension basis points into your pipeline P&L automatically and require sign-off above a set day threshold.
- Approvals disappear with no record. Route every reprice and extension through a workflow tool that timestamps the approver and the reason, not a verbal "go ahead."
Pro Tip: If you can't answer "who approved this reprice and why" in under thirty seconds, your audit trail isn't working, no matter how good your software looks on paper.
Rolling Out a Rate Lock Workflow Without Chaos
After twenty years watching brokerages rebuild the same broken process, my advice is simple: start smaller than you think you need to. Get the LOS working as your single source of truth, connect the PPE, stand up the borrower POS, and turn on a daily expiry report. That's the minimum viable version, and it's enough to expose most of your real problems.
Pilot it on a small batch of loans end to end before rolling out broadly. Two to eight weeks is typically enough, depending on your volume. Train loan officers, lock desk staff, and processors together, not in separate sessions, and enforce the new rules through dashboard visibility rather than memos. Collect feedback weekly during the pilot and adjust before you scale it across the whole shop.
— Omar Khamisa
How 1 Solution Mortgage Software Supports Your Lock Desk
The real cost of a fragmented rate lock process isn't the software fees. It's the rekeying, the missed expirations, and the reprices nobody can explain six months later. 1 Solution Mortgage Software was built by a broker, for brokers, specifically to close that gap: LOS, PPE, borrower POS, and CRM live in one connected platform instead of four disconnected logins.
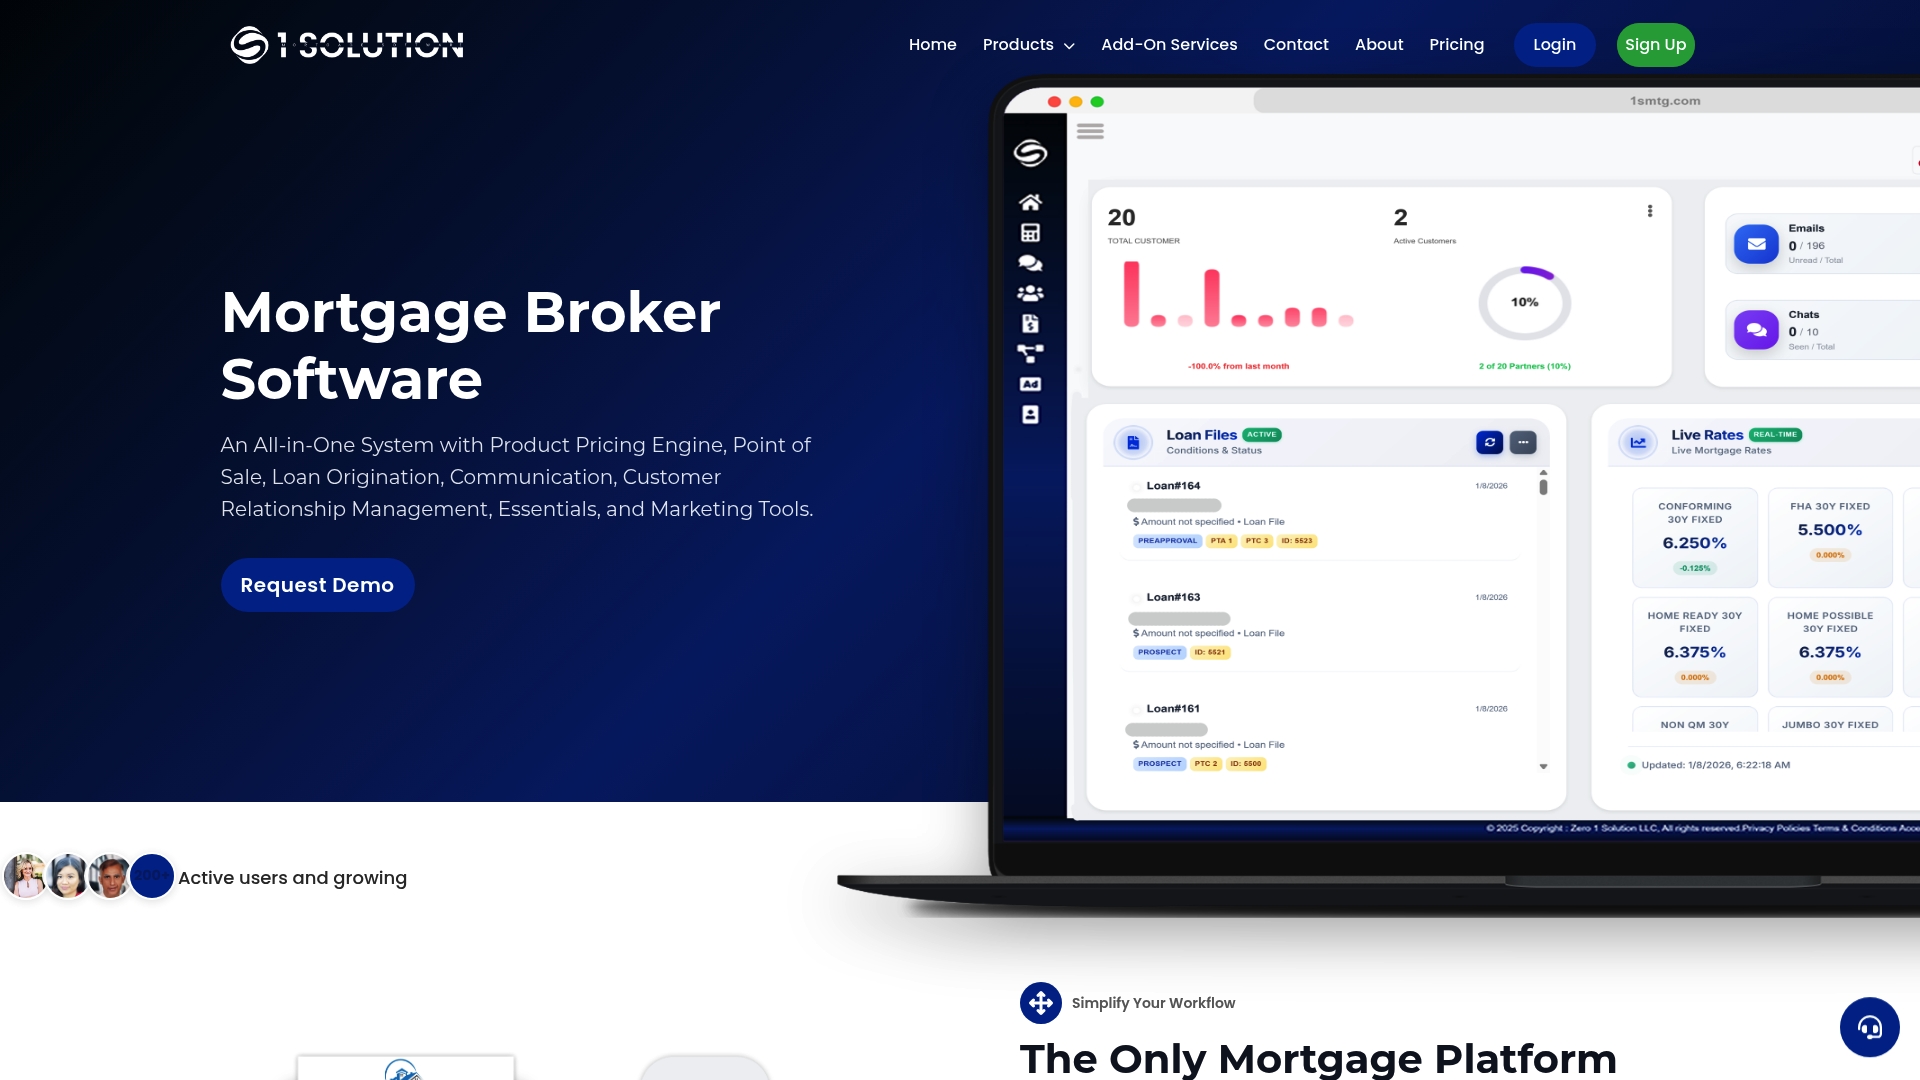
When pricing, locking, and borrower confirmation all run through the same system, a lock gets recorded once and shows up everywhere it needs to: the LOS file, the CRM communication log, and the daily expiry report your lock desk already checks. That's fewer touches per loan and one less place for a rate to quietly drift.
A demo walks through your current pipeline setup, identifies where PPE and LOS data are currently disconnected, and maps out onboarding steps for your team. Brokerages set the pace themselves rather than following an enterprise timeline built for banks. If you're ready to see what an integrated workflow looks like on your own files, start with a look at the platform and get pricing details straight from the source.
Sources
For deeper background on the practices referenced here, the Mortgage Bankers Association's lock desk best-practices white paper covers expiration tracking and approval structures in detail. For workflow design specific to your office, see our mortgage office workflow guide and our overview of closing coordination systems.
- Ready, set, lock! A guide to locking in your mortgage lock desk operations (MBA white paper)
- Document and workflow automation for mortgage risk control (Artsyl)
- Your borrowers miss rate locks because nobody called them in time (RunFrame)
- What is the best tech stack for a mortgage brokerage? (PulseRevOps)
FAQ
What Is the Difference Between a Rate Lock Workflow and a Pricing Engine?
A pricing engine (PPE) generates eligible, lockable quotes based on investor guidelines. The rate lock workflow is the broader process, including the PPE, the LOS, the lock desk, and borrower confirmation, that turns that quote into a committed rate through funding.
How Long Should a Rate Lock Period Be?
Lock periods vary depending on expected time to close, though longer periods usually carry a pricing cost. The right length depends on aligning the lock expiration with your realistic underwriting and closing timeline, not the shortest option available.
Who Approves a Rate Lock Extension?
Extension approval should sit with the lock desk or secondary marketing, not the individual loan officer, especially past a defined day threshold. Logging the approver's identity and the reason for the extension protects the file during a compliance or audit review.
Does 1 Solution Mortgage Software Include a Pricing Engine?
Yes, 1 Solution Mortgage Software's platform includes an integrated product pricing engine alongside its LOS, CRM, and borrower POS, so lock data doesn't need to travel between separate systems. Current subscription pricing is available directly on the 1 Solution website.
What Causes Most Missed Rate Locks?
Most missed locks trace back to delayed borrower confirmation or a loan officer who didn't act on an expiring lock in time. Locking while the borrower is still on the call, followed by immediate written confirmation, closes most of that gap.